Accountant Resume Builder
Create a professional ATS-friendly resume with customizable templates in minutes
Sign-up FREE. No Credit Card Required.
Create a professional ATS-friendly resume with customizable templates in minutes
Sign-up FREE. No Credit Card Required.
Trusted by 30k+ accountants, VisualCV combines polished design, ATS optimization, and AI guidance to help you spotlight close, reconciliations, and the results hiring managers want to see.
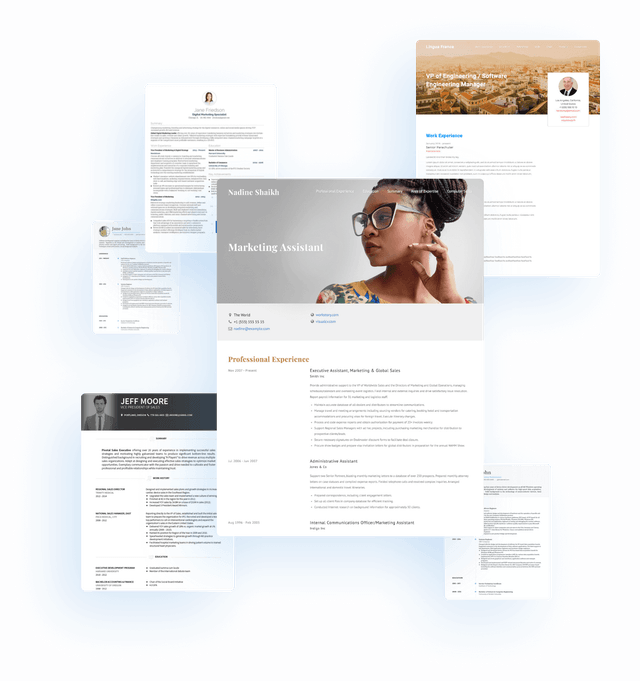
Explore accounting resume examples when you need to clarify how to present your work or find fresh inspiration. These job-winning resumes reveal the scope, skills, and achievements other applicants often miss.
For over a decade, we have researched and written specific resume, cover letter, and job search advice that is hard to find elsewhere. Use our free resources to pursue your next accounting role.

Use design tools that make it easy to balance a modern look with a professional tone. Every template has been tested and refined over a decade to support clear, credible accounting resumes.

Customize your resume for each accounting job with ease. VisualCV lets you tailor sections, keywords, and accomplishments, an underrated step that helps your application stand out to employers.

ATS-optimized, customized resumes are more effective, so after using VisualCV, you can focus on preparing clear interview stories and handling interviews with confidence for accounting roles.
VisualCV is the resume builder for accountants who want to overcome the challenge of creating a polished application.
Use a reverse-chronological, single-column format for an accountant resume. It lets a reviewer follow your progression from transaction or staff work into broader accounting-cycle ownership, including:
Standard headings and consistent dates support a linear reading order for people and applicant tracking systems. Use one page when your relevant accounting evidence is limited. A second page is justified when it preserves recent progression or specialization, accurately stated credentials, or material accounting-cycle scope. Before compressing, cut:
Keep recent accounting-cycle evidence, credential status, and role-specific systems instead.
Give the greatest visual priority to your most recent accounting role. Your title, employer, dates, and owned work should be easy to find before a reader reaches a skills list. A clean structure is:
Before: A two-column layout with a narrow sidebar of software names and a dense main column of duties.
After: A single-column layout that starts with your Senior Accountant role, then shows close ownership, balance-sheet reconciliations, reporting schedules, and review responsibilities. List systems compactly, then mention an ERP or Excel again only where it explains the task performed.
A combination format can make sense when you are moving from bookkeeping or finance operations into accounting and need to foreground transferable evidence before employment history. Keep the dated work record intact, then add a short evidence-based section for relevant reconciliation, general ledger, reporting, or coursework experience. Avoid a fully functional format that obscures dates, employers, and your level of responsibility. Whether a CV is appropriate also depends on local hiring conventions, so use one when the employer requests it or the market expects an academic or detailed professional record.
An accountant resume should let a reader quickly identify your accounting scope, the evidence behind it, and the level of responsibility you held.
Include a professional heading and contact details:
Use a role-specific headline, such as “Staff Accountant” or “Senior Accountant | Month-End Close & Financial Reporting.”
Use a short summary to state your accounting environment and the work you support, such as close, general ledger activity, reconciliations, reporting, or audit support. Use an objective when you are entering accounting, returning after time away, or changing from an adjacent finance role.
For each role, list the employer, location, title, and dates. Show the accounting process you handled and state whether you:
Transaction processing and subledger activity can feed the general ledger. Reconciliations validate balances. Close turns validated balances into schedules and reporting inputs. Audit support, controls, tax, and operational specialties are distinct downstream responsibilities, so identify the one you actually performed.
Example:
“Prepared balance sheet reconciliations for two entities and investigated exceptions before completing assigned close tasks by the reporting deadline.”
List your degree, institution, and graduation date when relevant. Include credentials or exam progress with an accurate status, particularly where the target role names a designation or specialization.
Include skills you can support through your work history:
Include internships, contract assignments, and operational roles when they show transferable financial work. Payables, receivables, billing, collections, expense processing, and bookkeeping can demonstrate transaction accuracy, records handling, or subledger experience. Do not relabel bookkeeping as accounting ownership unless you performed the related general ledger, close, reporting, or review responsibilities.
Build an accountant resume by matching verified accounting evidence to one target role, then ordering it into a focused record of relevant work. Start with a master version containing your full history, then create a copy for each vacancy so close, reporting, tax, or operational accounting experience does not get buried.
Identify the target accounting environment and role. Read the vacancy for its accounting focus, level of ownership, and work setting. Distinguish an industry close role from public accounting, tax, cost accounting, or an operational role. Carry forward only priorities you can support with real experience.
Select verified evidence from your master record. Pull the work that best matches the target, including reconciliations, general ledger activity, reporting support, audit documentation, or close coordination. Be precise about whether you prepared, reviewed, analyzed, coordinated, or owned the work. Use defensible scope without naming clients, disclosing internal-control issues, or sharing confidential financial figures.
Before: “Prepared reconciliations and assisted with month-end close.”
After: “Prepared bank and balance-sheet reconciliations, investigated exceptions, and completed assigned close tasks for three legal entities by the monthly reporting deadline.”
Order the evidence by relevance. Lead with the roles and accomplishments that most closely match the vacancy, even when older experience is more relevant than a recent unrelated position. Within each role, place the strongest target-role evidence first and keep transferable bookkeeping, payables, receivables, or administrative work in its accurate scope.
Validate every claim. Check each statement against your records before including it. Confirm dates, ownership, results, credential status, and system names. A tool belongs only when you used it in the work described, such as an ERP for general ledger activity or Excel for reconciliation analysis.
Run a final relevance and readability check. Remove material that does not support the role, then read the document as a hiring manager would. Your resume should show a clear accounting direction without overstating your experience or adding unsupported keywords.
Before submitting, confirm that the resume aligns with the target role, every claim is supported, credentials are accurate, named systems are relevant, and the length fits your experience without burying key evidence.
Describe your accounting experience by identifying the process and responsibility level, then showing how much or how complex the work was and what evidence supports it. Employers should be able to tell whether you handled general ledger maintenance, close, reconciliations, reporting, audit support, or control documentation, and whether you prepared work for review or held a higher level of responsibility. Do not claim ownership of financial statements, controls, tax positions, or audit conclusions when you prepared support for someone else’s review.
Give recurring work enough context to show its weight. Communicate scope through details such as:
Separate dependable execution bullets from judgment or escalation bullets when both reflect your role. An execution bullet can show that you completed recurring reconciliations, maintained close checklists, prepared adjusting entries, or assembled audit workpapers. A judgment bullet can show that you investigated an exception, analyzed a variance, resolved a supported discrepancy, or escalated an unresolved issue for review. Use verified numbers to quantify scale, volume, or deadlines. When a financial result is unavailable, use a supportable qualitative outcome, such as clearing reconciling items before close or organizing audit evidence for review.
Before:
“Prepared monthly bank reconciliations and journal entries.”
After:
“Prepared monthly bank reconciliations and related journal entries for assigned accounts, documented reconciling items, and cleared supported exceptions ahead of close.”
Example:
“Supported month-end close for multiple entities by preparing balance-sheet reconciliations, maintaining close documentation, and escalating unresolved intercompany differences for review.”
For reporting work, name the output and your contribution precisely. You may have prepared account schedules, consolidated source data, drafted management-report inputs, analyzed variances, supported disclosures, or reviewed completed outputs. Those distinctions help employers assess whether your experience fits a staff, senior, financial reporting, tax, public accounting, or management accounting role without overstating your authority.
Accounting accomplishments show that your recurring work was effective, not just assigned. A responsibility says you prepared journal entries or completed reconciliations. An accomplishment adds evidence that the work supported a timely close, reliable records, resolved exceptions, review readiness, control support, or a less manual workflow.
Build an accomplishment with a truthful action, the process or scope involved, and a defensible result. If you cannot support an outcome, a clear process bullet is preferable to implying one.
Before:
"Responsible for month-end close and account reconciliations."
After:
"Prepared month-end journal entries and reconciled balance-sheet accounts for three legal entities, resolving aged discrepancies before the close deadline."
The second version identifies the work, its scale, and evidence of effectiveness without claiming a dramatic financial gain.
Example:
"Standardized fixed-asset support schedules for the monthly reconciliation, reducing follow-up items during review."
Use figures from work you can explain, such as entities supported, reconciliations completed, reporting cycles, transaction volume, or days within a close schedule. When no exact figure is available, state the deadline met or the recurring scope rather than estimating an improvement.
Organize outcomes around the part of the accounting process that improved:
Do not turn every duty into an accomplishment. "Prepared 25 account reconciliations each month" is a useful process bullet when it accurately shows workload. Add a result only when you can describe what changed and your role in it.
Operational results are meaningful even when they do not affect revenue. A cleaner close, fewer unresolved items, dependable reporting support, and better documentation all demonstrate effective accounting work.
Example:
"Prepared balance-sheet reconciliation support for quarterly review, resolving documented exceptions and providing schedules ready for controller review."
For audit support, distinguish between preparing evidence, responding to requests, testing a control, and owning the control activity. For financial reporting, be equally precise about whether you prepared schedules, consolidated data, analyzed variances, or reviewed outputs. This keeps the accomplishment credible and shows where your contribution fit in the process.
Build each version around the target's level and accounting function, then adjust for its environment and any transaction-cycle focus, changing the order and detail of real evidence rather than your title or scope. When financial data is confidential, show scale through entities, account volume, reporting cycles, transaction volume, or deadlines instead of amounts or client names.
For staff roles, lead with work that keeps the ledger current and supports a reliable close. Emphasize journal entries, reconciliations, accruals, fixed assets, and whether you prepared, investigated, or reviewed each activity. For senior roles, bring forward close ownership, workpaper review, escalation judgment, process documentation, and coordination across teams.
Example: "Prepared recurring and non-routine journal entries; reconciled assigned balance-sheet accounts; resolved reconciling items before month-end close."
Before: "Completed month-end close and reconciliations."
After: "Owned close activities for assigned entities; reviewed reconciliation support; coordinated resolution of open items with AP, payroll, and operations teams."
For corporate accounting roles, prioritize general-ledger ownership, entity close work, intercompany activity, account analysis, and subledger-to-general-ledger ties. Do not turn transaction processing into broader ledger ownership unless you maintained or reconciled the relevant accounts.
Example: "Prepared intercompany entries and balance-sheet reconciliations for assigned entities, investigating differences before close."
Financial-reporting roles require precision about whether you prepared schedules, consolidated data, analyzed variances, drafted reports, or reviewed outputs. State reporting deadlines and the source records you used, but do not imply that you issued financial statements or owned disclosures when you prepared support for review.
Example: "Prepared reporting schedules and variance explanations for monthly management reporting using general-ledger data and supporting reconciliations."
Move operational evidence higher when the role connects to manufacturing, inventory, or planning. Focus on standard costs, inventory valuation, production variances, margin analysis, budgeting, or forecasting only where you performed that work; general close experience should support the operational story.
Example: "Analyzed material and labor variances; investigated inventory movements with production teams; prepared monthly cost reporting for management review."
Identify the tax work you actually handled, such as compliance support, provision work, research, filing coordination, client requests, or authority correspondence. State your role accurately when a reviewer, manager, or authorized signer made the final decision or submission.
Example: "Coordinated source documents and workpapers for recurring tax filings; tracked filing deadlines; responded to information requests under senior review."
For external public-accounting engagements, emphasize client service, workpapers, testing, documentation quality, and competing deadlines. For internal audit or controls work, distinguish testing controls, maintaining evidence, remediating issues, and owning control activities. For industry audit support, frame close and reconciliation experience as audit-ready support and responses to requests, not engagement ownership.
Example: "Prepared organized reconciliation support and account analyses for audit requests, resolving documentation gaps with internal stakeholders."
Foreground project billing, revenue support, contract or cost tracking, and coordination with project managers. Keep the evidence tied to the project lifecycle rather than presenting it as general-ledger ownership.
Example: "Tracked project costs and billing support, investigated coding exceptions, and coordinated documentation with project managers."
For AP, lead with invoice processing, payment runs, vendor reconciliations, expense workflows, and exception resolution. When applying to a broader accountant role, use AP as transferable evidence of transaction accuracy and reconciliation discipline, not as a substitute for general-ledger ownership.
Example: "Processed invoices and payment support, reconciled vendor statements, and resolved approval or coding exceptions."
For AR, emphasize billing, cash application, customer-account reconciliation, collections support, and aging analysis. For broader accountant roles, connect this work to account investigation and clean supporting records without overstating ownership of the ledger or close.
Example: "Reconciled customer accounts; applied incoming payments; investigated billing discrepancies and maintained aging support for follow-up."
Do not hide bookkeeping experience when applying for junior or staff accountant roles. Reframe transaction classification, bank and card reconciliations, payables or receivables support, and month-end preparation as transferable accounting-cycle evidence, then state the boundary honestly if you supported close rather than owned the general ledger.
Example: "Maintained transaction records and completed monthly bank reconciliations, preparing organized support for the accountant's close and reporting process."
Use accounting terms that accurately describe your work, then prove the most important ones in your summary and experience bullets. A focused skills section helps recruiters and applicant tracking systems identify fit, but terms such as month-end close or GAAP carry weight only when your resume shows the work behind them.
Read the vacancy for its accounting processes, reporting responsibilities, control work, and specialization. Select a small, role-specific subset of supported terms. If it calls for balance-sheet reconciliations, do not substitute the broader word “reconciliation” when you can truthfully name the account type. Use intercompany accounting only when you performed a recognizable part of that process.
Explicit keywords worth using
Place established task names in a skills section when you can support them elsewhere. Demonstrate terms that describe responsibility or judgment in experience bullets, including close ownership, report preparation, consolidation, control testing, issue remediation, and review. Do not claim a framework, specialty, or senior-level responsibility without underlying task history. GAAP is a conditional claim, appropriate when you applied it in relevant accounting or reporting work, not a universal accountant keyword.
A staff accountant may prioritize journal entries, reconciliations, close, and supporting schedules. A senior accountant may add review, coordination, escalation, and process documentation. Cost, tax, public accounting, and project accounting roles need their own precise vocabulary rather than a generic skills list.
Some terms are better treated as evidence than standalone skills. Accuracy, attention to detail, problem solving, and Microsoft Excel become credible when tied to actual accounting work. Name the process and state whether you prepared, reviewed, approved, coordinated, or owned it. Add defensible scope or an outcome when available.
Weak: “Excel, reconciliations, attention to detail, financial reporting.”
Better: “Reconciled balance-sheet accounts in Excel and investigated exceptions with operational teams; prepared supporting schedules for the monthly close.”
This structure distinguishes reconciliation work from a keyword and shows its connection to supporting evidence, exception resolution, and the close deadline. It also makes your ownership level clear.
Use a compact skills section with categories that match your background. Prioritize the terms repeated in the vacancy that you can also substantiate in experience, rather than listing every process you have encountered.
A keyword belongs on your accountant resume only if you can explain it in an interview with a real example. That standard keeps ATS alignment truthful and prevents a dense list from obscuring the accounting work you can actually perform.
List systems you have used in a compact Technical Skills section, then repeat one in experience only when it explains meaningful work or a supported result. A software-name dump does not show what you did with a tool.
Use a separate skills section when platform range is relevant but work history cannot show it clearly. Keep a system only in Technical Skills when you cannot give it useful context in experience. Name it in experience when it explains a material responsibility or result. Use a generic category, such as “ERP system” or “close-management platform,” if an internal or confidential name would disclose nonpublic information. Do not assign proficiency labels unless you can explain the work behind them.
After:
“Used Excel for balance-sheet reconciliations and variance investigations, preparing schedules for month-end close.”
List an accounting credential in the header only when you hold an active designation you are entitled to use. Otherwise, place it in a Credentials section directly below Education. Keep the credential name with its issuer or jurisdiction, then state its current status in the same entry. Do not use an unfinished designation after your name.
A degree records academic study, while a credential or designation records a completed professional qualification. A license records authorization only when active, and exam progress records verifiable milestones rather than a qualification held. Eligibility states your position relative to a requirement; membership and continuing education show affiliation or recent learning, not authority. These terms can differ across jurisdictions and specialties, as well as among employers.
If you do not hold a CPA or equivalent designation, lead with your degree and relevant accounting-cycle experience. Add supported coursework or exam progress when applicable, then qualifications that match the role. Do not compensate with ambiguous credential language. Never imply authority you do not hold, including a license or permission to sign or practice.
Before: “CPA, 2026”
After: “CPA examination: 2 of 4 sections passed, 2026”
Example: “Certified Public Accountant: active status with the issuing jurisdiction”
An accountant resume with no direct experience should lead with verifiable accounting-adjacent work and state exactly what you prepared, supported, or learned, rather than claiming ownership of a close, general ledger, or financial statements. Give the reader evidence that you can work carefully with transactions, documentation, deadlines, and financial data.
Use experience that connects to the accounting cycle, even if your title was not Accountant:
Separate paid work from academic projects, and use ownership words precisely. “Assisted with,” “prepared,” “maintained,” and “reconciled” describe different levels of responsibility. If you used Excel or an accounting system, connect it to the task you performed. You can show scale without revealing confidential balances, clients, or control issues by naming the type of records, reporting cycle, or process involved.
Before: “Managed month-end close and created financial statements.”
After: “Completed an accounting coursework project that recorded adjusting entries, reconciled a sample bank account in Excel, and prepared draft financial statements from a trial balance.”
This wording gives an entry-level accountant resume credible technical detail while keeping the boundary between classroom practice and professional accounting responsibility clear.
Choose a layout that keeps job titles, dates, ownership level, credentials, and close or reporting scope easy to find.
Best when your accounting progression and review responsibility are visible across roles. Keep each position’s dates beside the title and show whether you prepared, reviewed, or owned reconciliations, close, and reporting.
Example:
"Senior Accountant | Jan 2023 to Present | Reviewed balance-sheet reconciliations and coordinated month-end close for three entities."
Best when you need to fit several scoped accounting roles, credentials, and systems without losing dates. Use clear role entries to separate work in payables, fixed assets, intercompany accounting, audit support, or financial reporting, while preserving your ownership level.
Best for entry-level accountants and transition candidates who need education, internships, and credential progress visible. Keep work history central, but give relevant coursework, internship close or reconciliation support, and accurate credential status a clear place.
More specifically, name the close activities you actually performed or owned, such as preparing journal entries, reconciling balance-sheet accounts, maintaining close checklists, investigating variances, or compiling reporting schedules. Add the number of entities, accounts, or reporting deadlines involved when that information can be shared safely.
Use verbs that state your true level of responsibility: prepared, reconciled, analyzed, reviewed, approved, coordinated, or led. For example, preparing a consolidation schedule is different from reviewing it for accuracy or owning the reporting process, and senior-level resumes should make that distinction especially clear.
Specify the reconciliation type when it demonstrates relevant experience, such as bank, balance-sheet, intercompany, payroll, inventory, fixed-asset, or subledger-to-general-ledger reconciliations. This gives employers a clearer picture of your accounting cycle responsibilities than the word reconciliations alone.
Use defensible measures of scale and process rather than sensitive financial figures, such as entities supported, accounts reconciled, monthly reporting cycles, transaction ranges, close deadlines, or aged items resolved. You can also describe a percentage or time improvement only when it is accurate and does not reveal protected company information.
State the exact credential status, such as CPA, active license with jurisdiction listed where useful, CPA candidate, exams passed, or eligible to sit, only if each description is accurate. Do not present exam progress, coursework, membership, or eligibility as an active license, because credential rules vary by jurisdiction and employer.
Use relevant evidence from internships, bookkeeping, accounts payable or receivable work, academic projects, volunteer finance duties, and transferable administrative roles. Describe the accounting tasks performed, such as invoice processing, account analysis, Excel reporting, expense review, or transaction entry, without overstating responsibility.
Use terms from the vacancy only when your background supports them, prioritizing named responsibilities such as month-end close, general ledger, financial reporting, reconciliations, variance analysis, audit support, or accounts payable. Match the employer's wording naturally in your summary, experience, and skills rather than adding unsupported keywords.
Use a summary when you can quickly establish relevant accounting experience, specialization, systems, and results, such as close support, reporting, audit preparation, or multi-entity reconciliations. An objective is more useful for students, career changers, and returners who need to explain their target accounting direction before they have a substantial record.
Use a second page when you have enough relevant experience, credentials, systems knowledge, and accomplishments to fill it with useful evidence. Early-career accountants can usually be concise on one page, while experienced candidates may need more room for senior review duties, public accounting engagements, specialized reporting, or complex close ownership.
Choose verbs that match the work you performed, including prepared, posted, reconciled, analyzed, reviewed, resolved, documented, coordinated, improved, and led. Pair each verb with the accounting activity and scope, such as reconciled 60 balance-sheet accounts or coordinated close deliverables for three entities, so the bullet shows both action and responsibility.